 Vijay Singh
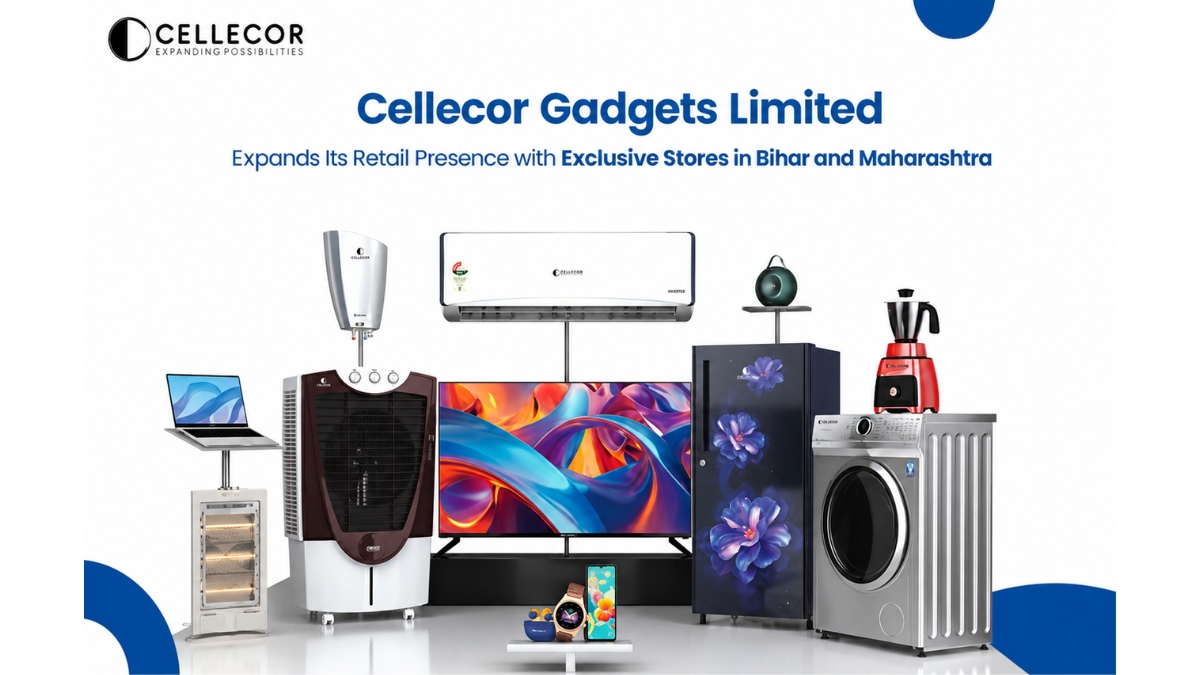
Mumbai (Maharashtra) [India], August 27: Cellecor Gadgets Limited is emerging as a fast-growing affordable consumer electronics and appliances brand, with its expanding distribution network, improving margins and international expansion plans drawing attention from investors. In its research report dated August 26, 2026, SEBI-registered research firm LNPR Capital placed the stock on a “Watchlist — Constructive” basis, citing significant growth optionality while highlighting execution, dilution and disclosure risks.
According to the report, Cellecor has grown its revenue from ₹264 crore in FY23 to ₹1,292 crore in FY26, representing a three-year compound annual growth rate of around 70%. During the same period, EBITDA margin improved from 4.8% to 5.54%, while the company reported a return on equity of 22%. LNPR Capital highlighted the company’s distribution footprint as a key competitive advantage, with more than 100,000 retail touchpoints, over 1,800 distributors, 2,000-plus service centres and service coverage across more than 25,000 pin codes.
The company follows an asset-light business model, with manufacturing outsourced to established players including Dixon Technologies, PG Electroplast, Elin Electronics and Zetwerk, among others. LNPR Capital noted that Cellecor has been able to scale rapidly with gross fixed assets of only around ₹18 crore, supporting its capital-light growth model.
Cellecor’s financial performance has continued to improve. Revenue increased from ₹1,026 crore in FY25 to ₹1,292 crore in FY26, while EBITDA rose 32% year-on-year to ₹71.54 crore. Profit after tax increased 28% to ₹39.61 crore from ₹30.90 crore. EBITDA margin improved to 5.54% from 5.29%, while PAT margin stood at 3.07%.
The report also pointed to an improvement in cash generation. Cellecor reported its first positive operating cash flow in its listed history in FY26 at ₹1.1 crore, while free cash outflow narrowed to ₹20.83 crore from ₹64 crore in FY25. However, LNPR Capital noted that the improvement was partly supported by higher trade payables, while trade receivables also increased as the company expanded its presence in modern trade and large-format retail.
One of the major near-term catalysts identified by the research firm is Cellecor’s proposed migration from the NSE EMERGE platform to the NSE Main Board, along with a simultaneous direct listing on the BSE Main Board. The company’s Board approved the proposal on August 6, 2026, with shareholder voting scheduled through September 6, 2026. LNPR Capital believes a main-board listing could improve liquidity, investor eligibility and price discovery for the stock.
Another major component of Cellecor’s growth strategy is its proposed manufacturing platform in Liberia. The company has raised approximately $33 million through foreign currency convertible bonds and deployed $29.02 million into Cellecor Gadgets Europe Ltd, which is expected to support the Africa expansion. A preliminary, non-binding Heads of Terms was signed for a site of around 15 acres in the Buchanan Special Economic Zone in Liberia for manufacturing, assembly, testing, packaging, warehousing and exports.
The research report highlighted Africa’s large consumer electronics opportunity, particularly in affordable appliances. It noted that the African consumer electronics and appliances market is estimated at more than $60 billion annually, while West Africa represents a market of more than 400 million people across the 15-member ECOWAS bloc. LNPR Capital believes Cellecor’s experience in affordable products and after-sales service could provide an opportunity to build a presence in the region.
However, the research firm has adopted a cautious approach towards the timeline for the Africa project. Cellecor’s management has indicated a potential ₹450 crore revenue contribution in the first year and ₹1,500-2,000 crore within two to three years. LNPR Capital, however, said it would model Africa revenue only from FY29 and treat the ₹450 crore figure as an ambition rather than a base-case forecast, given that the Liberia project remains at an early stage.
The report also flagged potential dilution as an important factor for investors. Cellecor currently has 22.23 crore shares outstanding, while promoter warrants, ESOPs and the FCCB could substantially increase the share count. Depending on the eventual FCCB conversion price, LNPR Capital estimates potential dilution of around 52%-63%. The FCCB conversion price remains undisclosed, making fully diluted valuation difficult to determine at present.
At a market price of ₹34.50 as of August 26, 2026, Cellecor had a market capitalisation of approximately ₹766 crore. The stock was trading at around 19.4 times reported earnings, while LNPR Capital estimated the fully diluted valuation at closer to 30 times earnings, compared with a peer median P/E of approximately 28 times.
LNPR Capital has not assigned a formal Buy recommendation at this stage. Instead, it has classified Cellecor as a “Watchlist — Constructive” stock, with a formal call dependent on factors including disclosure of FCCB conversion terms, delivery of H1 FY27 performance in line with expectations, completion of the main-board migration and progress on the Liberia manufacturing project.
The report also highlights several risks, including execution risks surrounding the Liberia project, currency exposure from the dollar-denominated FCCB, potential dilution, working-capital requirements and relatively thin EBITDA margins. LNPR Capital also pointed to limited disclosure, the absence of concall transcripts and board-level concentration as factors investors should monitor.
Overall, LNPR Capital believes Cellecor represents a high-optionality growth opportunity, combining rapid domestic expansion with potential international manufacturing and distribution. However, the research firm has emphasised that the stock remains a watchlist opportunity rather than a formal investment call until key milestones around FCCB terms, FY27 execution and the main-board transition are confirmed.